Katy sits in a hail corridor. Storms rolling in from the west drop hail on Cinco Ranch, Seven Meadows, and Firethorne, and on the 77494 and 77450 ZIP codes, season after season. One hard storm can mark up thousands of roofs in a single night.
When that storm is yours, the order you do things in matters. Good proof and a fast claim can be the difference between a paid roof and a denied letter. This guide walks through the claim process in plain words, step by step, with the deadlines Texas law puts on your insurance company. If the roof needs the work done after the claim, that is our daily job: hail damage repair in Katy.
The claim process, step by step
Step 1: Document the damage with photos
Wait until the storm has passed and it is safe to go outside. Shoot the whole roof from the ground, one slope at a time. Then get close shots of cracked, bruised, or missing shingles. Photograph dented gutters, downspouts, vents, AC unit fins, and window screens. Hail hits on soft metal help prove the storm hit hard enough to wound shingles too.
Put a coin or a ruler next to hail stones and next to damaged spots so the size shows in the photo. If the storm just passed, save a few hail stones in the freezer with the date noted. Shoot the inside of the house as well: ceiling stains, drips, wet attic insulation. Write down the storm date and time. Weather records for that date can back you up later.
Hail damage on a shingle is easy to miss from the ground. Bruised spots feel soft under the mat and shed granules fast. Our guide on the signs of hail damage on a roof shows what to look and feel for.
Step 2: Make temporary repairs, and keep every receipt
Your policy expects you to stop the damage from getting worse. Cover broken areas so rain stays out. Emergency tarping in the Katy area runs $400 to $1,500. Keep every receipt and invoice. Temporary repair costs are often paid back as part of the claim.
One hard rule: do not make permanent repairs before the adjuster sees the roof. A slope fixed too soon can wipe out the proof your claim stands on. Stop the water, save the proof, and wait for the visit.
Step 3: Call your insurance company within 24 to 48 hours
Call the claim line and give them your policy number, the storm date, and a short list of what you found. Write down the claim number and the name of every person you speak with.
Many Texas policies give you up to one year from the storm date to file. Do not use that year. Storms stack up in Katy. A second storm makes it hard to show which storm caused which damage, and insurers use that confusion to shrink claims. Filing within days keeps your storm, your date, and your damage tied together.
Step 4: Get your own roof inspection before the adjuster visit
The adjuster works for the insurance company. You need your own set of eyes on the roof first. A roofer walks each slope, chalks the hail hits, counts hits inside test squares, and shoots a photo report of every slope.
That report tells you what a fair settlement looks like before anyone quotes you a number. It also means no slope gets skipped because nobody climbed up to look at it. This is the core of our free roof inspection in Katy: photos, chalk marks, and a written report you can hand to the insurer.
Step 5: Meet the adjuster, with your roofer present
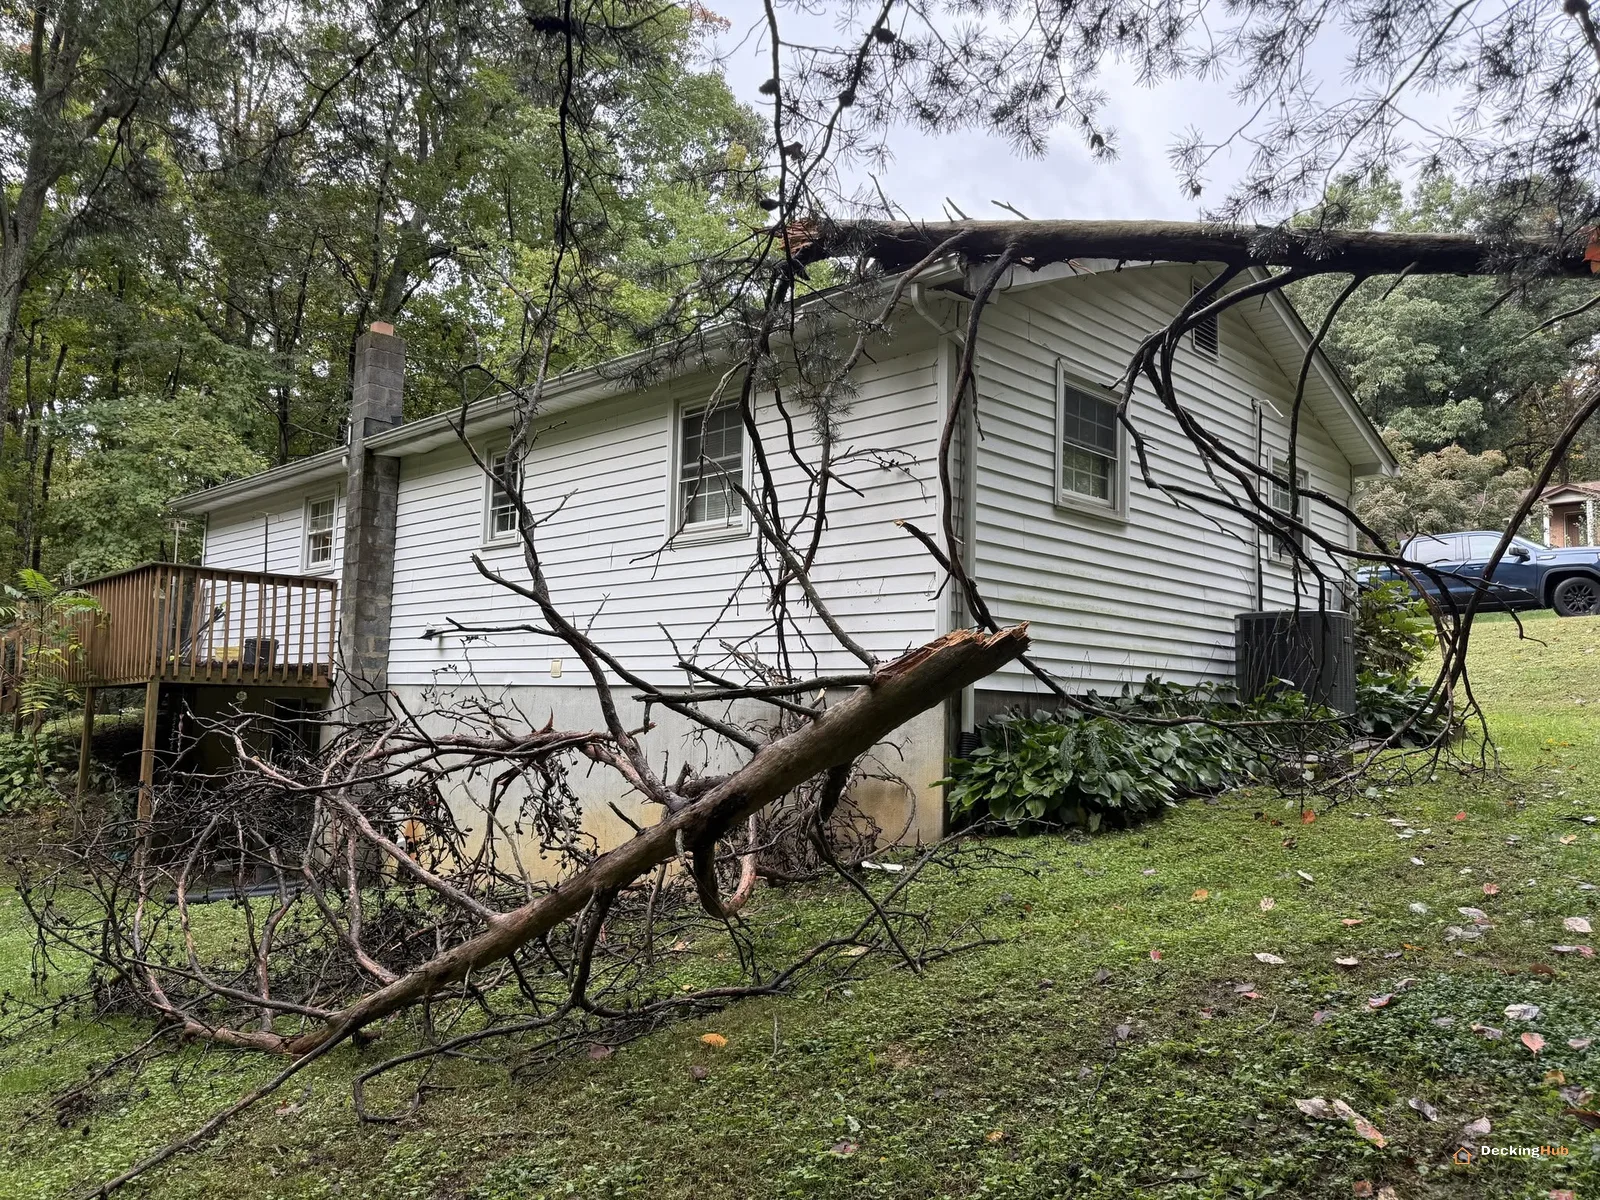
Be home for the visit. Walk the property with the adjuster. Your roofer can point to the chalk marks and test squares and walk through each hit on the spot, while the adjuster is standing there to see it.
An adjuster who sees clear proof in person makes a different call than one who reads a thin file a week later. Hand over your photos, your storm date, and your roofer’s report. Keep the talk on facts and dates.
Step 6: Read the settlement before you agree
Compare the settlement with your roofer’s estimate line by line. Low settlements often miss a whole slope or skip parts that always get replaced with the roof, like flashing and drip edge. Check which slopes were counted and which were not.
If the number comes in low, you have moves. Send in more proof and ask for a second look and a new inspection. Most Texas policies also carry appraisal rights: each side picks an appraiser, the two appraisers pick an umpire, and that panel settles the gap on price.
Texas timelines your insurance company must follow
Texas law puts clocks on a claim. Once you file, the insurer must acknowledge your claim within 15 days. After you send the proof they ask for, they have 15 to 45 days to accept or deny the claim. Once you and the insurer agree on a settlement, they must pay within 5 business days.
Keep a folder for the claim: photos, receipts, letters, emails, and notes from every call with dates. If a deadline slips, that folder is your proof. The Texas Department of Insurance explains your rights in plain words on its page about insurance and your roof. Read it before the adjuster visit, and use the TDI complaint process if an insurer stalls or stops answering.
The deductible decides if a claim makes sense
Most Texas policies carry a separate wind and hail deductible. It is set as a percent of the home’s insured value, often 1% to 2%. It is not a flat fee, and it shocks a lot of homeowners the first time they see it.
So run the numbers before you file. A claim that pays nothing still sits on your record. A claim for a wrecked slope, where the work runs well past the deductible, does the job insurance is there for. If you want the full picture of what policies pay for and what they skip, our guide on whether homeowners insurance covers roof repair walks through it.
Call (281) 677-8586
What not to say to the adjuster
Stick to facts: the storm date, what you found, and when you found it. Short, true answers protect the claim.
Do not guess at causes. Saying the roof was old anyway, or that a leak has been there for a while, hands the insurer a reason to pay less. Old wear and sudden storm damage get judged in separate buckets, and loose words can move real hail damage into the wear bucket.
Do not pin the damage on an older storm or on a date before you owned the home unless you know it for sure. Dates drive coverage. Do not agree to a cash settlement on the spot if the number feels low. You can take time, get your own estimate, and answer later.
If the claim is denied or paid too low
A denial is not the end of the road. Ask for the reason in writing. The insurer has to explain the decision.
Then build the file up: your roofer’s photo report, weather records for the storm date, and a written scope of the damage slope by slope. Ask for a new inspection with a different adjuster if the first visit missed damage. If the fight is about price rather than damage, use the appraisal clause in your policy. And if the insurer misses the legal deadlines or goes quiet, file a complaint with the Texas Department of Insurance.
Hail damage claim questions
Should you file a claim for hail damage on your roof?
File when the damage clearly passes your deductible and the storm date is solid. If the repair is small, say a few bruised shingles at $300 to $800, and your deductible is several thousand dollars, pay out of pocket and keep the claim off your record.
What not to say to an insurance adjuster about your roof?
Do not guess at causes, do not call the roof old or worn, and do not blame an older storm. Give the storm date, show the damage, and let the photos talk. Take time before you accept any settlement number.
How much does insurance pay for hail damage on a roof?
The insurer pays the covered repair or replacement cost minus your wind and hail deductible. With replacement cost coverage, payment often comes in two parts: a first check based on the roof’s cash value, then the rest once the work is done and invoiced.
How long after hail damage can I submit a claim?
Many Texas policies allow up to one year from the storm date. File within 24 to 48 hours anyway. Later storms blur which damage came from which date, and that blur works against you.
Will insurance cover a 20 year old roof in Texas?
It can cover sudden storm damage on an older roof, but many policies pay less as the roof ages, settling at cash value instead of full replacement cost. Age and wear alone are never covered.
Will filing a roof claim raise my rates?
Storm claims are a normal event in Katy, and one claim on its own is not the main risk. The real waste is a claim that pays nothing because the damage sat under the deductible. That claim still counts on your record. Run the deductible math first.
Call (281) 677-8586
Lines open 7 AM to 9 PM.
Once the claim lands, the roof still needs the work done right. See how our hail damage repair in Katy handles the repair side, from chalk marks to the last shingle. For leaks and other storm fixes, start with our roof repair team in Katy.